Times are challenging for law firms. Yet many bury their heads in the sand or are not proactive enough about actively managing cash. Even the most experienced managing partners in the savviest firms are looking afresh at old and new ways to improve profit and cashflow—which, of course, are not the same thing.
Let’s look at some quick ways to improve cashflow and some strategies for boosting profit through better billing.
Quick wins for improving cashflow
- Review your hourly rates. Don’t be put off by guideline rates. Price appropriately and avoid reducing prices simply to compete with peers. Build genuine differentiators, increase your rates and compete on your own terms while providing real value to clients.
- Consider referral fees. Subject to the applicable rules, you can often make a greater margin by referring work you do not cover to a friendly firm—which may refer work to you in turn—than by accepting low-value work for the sake of it. If you do take the work, scope it properly, complete it at the right level and charge for anything extra.
- Identify your cash pinch-points. Review the timing of payments in and out. Speak to suppliers where necessary and improve your debt-collection terms. I call unpaid sums debt, not outstanding invoices, because proper upfront payment for fixed fees or money-on-account policies for hourly work should minimise outstanding invoices. You may also find it helpful to align your financial year-end with your strongest cash period.
- Review the interest rate on your client account. Some banks offer considerably better rates than others, which can make a meaningful difference to a firm. Any arrangements must, of course, comply with the SRA Accounts Rules and your obligations to clients.
- Give debt recovery clear ownership. If you are owed significant client debt, dedicate a member of staff to calling and emailing debtor clients. Where appropriate, a slightly lower amount paid now may be better than a larger amount paid much later.
- Take fixed fees upfront or money on account for estimated work. Consider a lower fee for immediate payment and a higher overall fee where payment is spread over instalments. Your firm is not a bank.
- Define the retainer and charge for work outside it. Scope estimates and fixed fees properly. Estimates should be appropriate at the outset, revised when circumstances change, updated before they are exceeded and renewed for new phases or entirely new work. An estimate for drafting should generally cover the first draft only, with updates, revisions, comments and further exchanges charged separately. For fixed fees, use positive and negative assumptions—what is and is not covered—and account for time, complexity, urgency, value and the demands of the client.
- Find the leaking buckets. Is money being lost through complaints, inefficiencies, inactive files, poor debt recovery or missed billing? Every day, consider BCDE: billing, cash, debt and expenses—the pillars of financial discipline.
- Consider billing twice monthly. This can improve cashflow and help clients budget, particularly in areas such as family law. Work in progress should generally be billed or written off at month-end unless there is a good reason for it to remain unbilled, such as a contingent matter.
- Examine profitability by work type, department and fee earner. Compare your pricing with the market, the value delivered, overheads and margins. Every piece of work should be profitable; otherwise, profitable departments can mask unprofitable ones. Gross profit margin can be an even better indicator.
- Remember the value of existing, current and former clients. Check in regularly, consider a client relationship manager, use your database for useful newsletters, cross-refer and identify opportunities to help clients in other service areas. A simple grid of your service lines against your top clients can reveal where they have not yet used you—and prompt a valuable conversation.
- Ask when work has exceeded an estimate or fixed fee. First remind the client of the work completed and the benefit and value delivered. Then ask: “I’m in your hands, but do you mind if I bill you for [a portion of the difference]?” You may be surprised by the response.
- Increase prices when demand supports it. If you are busy, converting every enquiry or encountering no resistance to your prices, increase them.
- Do not assume that clients cannot pay until later. For work such as corporate sales or deferred-funding matters, ask for payment and then take an informed view.
- Structure payment options deliberately. You might offer a better price where everything is paid upfront and a higher total where payment is split—for example, £5,000 paid in full now compared with £6,000 across two instalments.
- Charge more when you are waiting for your money. The funding cost and additional risk should be reflected in your terms and pricing.
- Make bills payable on demand. Subject to your terms and regulatory obligations, consider interest and reasonable chasing costs where clients do not pay promptly.
Better billing
I could fill hundreds of pages with ways to improve billing, but these are some of the most useful places to begin.
- Analyse competitor pricing and increase yours where appropriate. Embed value and genuine differentiators. Help clients compare like with like: a rock-bottom headline price may look very different once add-ons and service quality are taken into account.
- Aim for fewer, better-quality and better-paying clients. Move inactive files forward, delegate, prioritise and organise so that work is progressed diligently at the right level.
- Discuss benefits and value before price. Understand your value and the difference you make to clients’ lives. Price work with regard to that value, your differentiators, tangible factors such as size and complexity, less tangible demands and an appropriate cushion.
- Get estimates right. An estimate for three hours at £300 per hour is not automatically £900. It should reflect the wider factors above and include enough headroom to avoid constant revisions.
- Make proper case notes. Record your strategic thinking and actions on a matter. Good notes protect you and the time spent creating them is chargeable.
- Hold a “this is how we work” meeting with new clients. Set boundaries and rules of engagement. This also helps you identify clients who may create additional work so that you can decline the instruction or price it accordingly.
- Charge appropriately for urgent, out-of-hours, complex and high-value work. The same applies to work outside the agreed scope. There is nothing wrong with using a range of hourly rates.
- Protect focused working time. Complete chargeable work in blocks, ideally in the morning, and focus on one matter at a time. Set sensible interruption boundaries with clients and colleagues. A carefully worded email response explaining when you check messages can reduce traffic and help you progress client work.
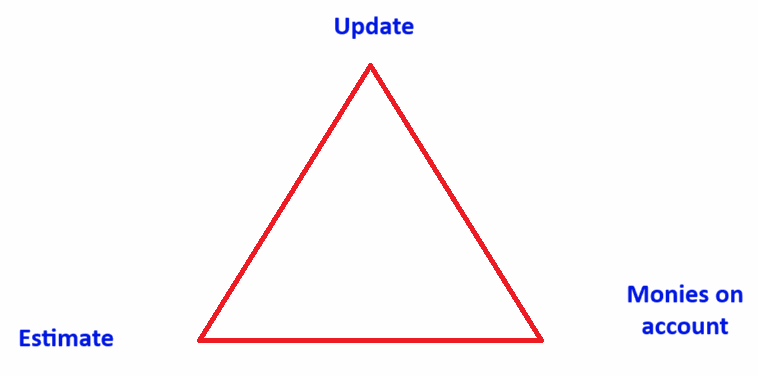
- Use the magic triangle. At regular intervals, verbally connect three things: update the client on progress and value delivered; provide an estimate for the next phase; and request matching money on account. This reduces debt and can make month-end billing largely administrative.
- Record all your time, bill all your time and get paid promptly. Avoid discounting or shaving time at any stage.
- Keep a time-and-motion diary. Identify where efficiency is being lost and consider TPDO: teamwork, prioritisation, delegation and organisation. There are eight hours in a working day—understand what happens to the non-chargeable time.
- Know your self-worth and value to the client. Do not be afraid to charge properly. You have years of knowledge, skill and experience and are helping clients improve their lives by solving problems that not just anyone can solve.
- Make tomorrow’s to-do list the night before. Colour-code tasks by urgency so you know exactly where to focus. Not every important task is urgent, and many tasks are neither despite feeling that way.
- Record time contemporaneously. Do not leave it until the end of the day. Keep a simple note of units or minutes as you work and enter them into the system promptly; otherwise, valuable time will be forgotten.
- Do not give away long initial consultations. A trained paralegal or PA can handle new enquiries, communicate value and direct suitable prospects into a paid consultation. This should produce better-quality clients who expect to pay for expertise.
- Record the time actually spent. Do not assume a task can only be recorded at a limited level because “that is how long it should take” or because a more senior colleague might complete it faster. Under-recording creates a damaging cycle. Firm-wide write-off protocols, including approval above a set threshold, can help.
- Do not discount, under-estimate or over-service. Charge properly for the value you deliver.
Put financial discipline into everyday practice
Actively consider cashflow, billing, estimates, fees and time recording. Make sure you charge properly and get paid well—without unnecessary discounts—for the value you bring to your clients.
Jay Sahota is a mentor, non-executive director and trainer to law firms of all shapes and sizes. He runs a day-long course on maximising billing, time recording, fees, costs and pricing. To discuss his training and mentoring, book a strategy call with Jay.
This article provides general business guidance. Firms should apply their own professional judgement and ensure that pricing, client-account arrangements, retainers, interest and recovery practices comply with the SRA Accounts Rules, applicable regulation and their terms of business.